
If you are shopping for a home in Yucaipa or Redlands, there is one phone call I would rather have you make early than late:
Call an insurance professional and get a homeowners insurance quote on the property.
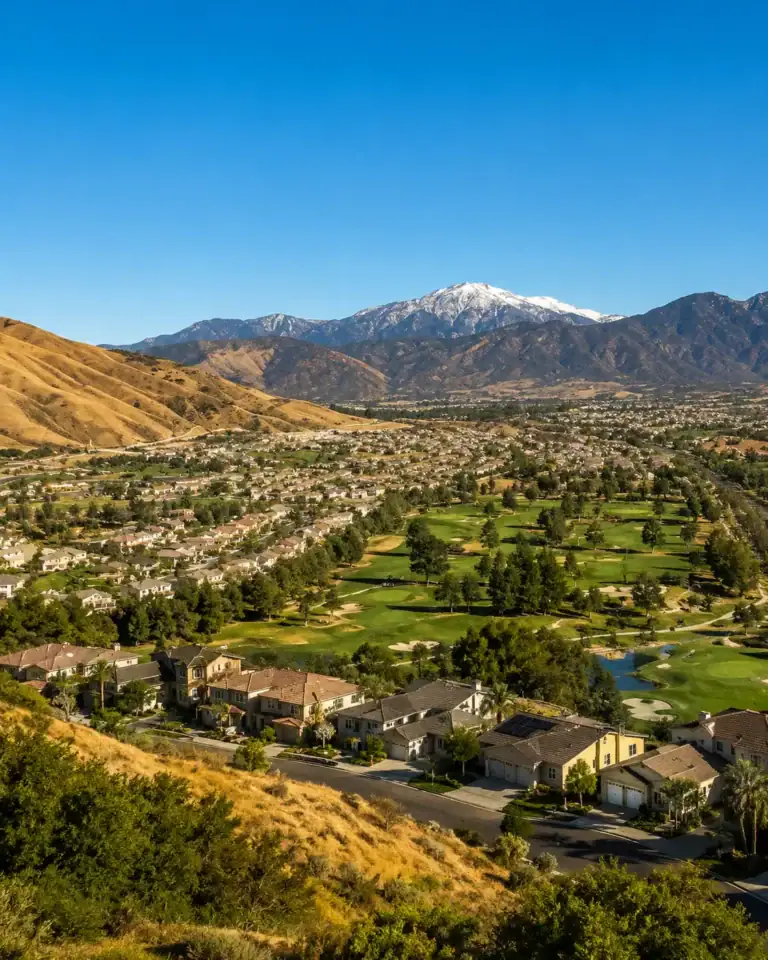
Home insurance in Yucaipa and Redlands deserves to be part of the home-buying conversation because portions of both communities are within mapped wildfire-hazard areas.
But there is also a lot of confusion about what those maps actually mean.
Here is the important part: a Fire Hazard Severity Zone designation does not automatically tell you what your insurance will cost—or whether a particular company will insure the home.
California’s Office of the State Fire Marshal explains that Fire Hazard Severity Zone maps measure wildfire hazard, while insurance companies use their own models when making insurance decisions.
So rather than panic over a map—or ignore insurance until the end of escrow—the smart move is to investigate the property early.
Let me walk you through what I would want a friend or client to know before buying a home in Yucaipa or Redlands.
Why Home Insurance Should Be Checked Early
Imagine finding the house.
You love the kitchen.
You love the yard.
You can already picture where the furniture will go.
Then, several days into escrow, you start calling insurance companies and discover that the premium is substantially different from what you expected—or that the first company you call does not want to write the property.
That is not the time I want you learning about insurance.
Homeowners insurance can affect your:
- Monthly housing budget
- Mortgage approval
- Cash needed before closing
- Choice of property
- Overall comfort with the purchase
If you are financing the home, your lender will generally require acceptable homeowners insurance before the loan can close.
My advice is simple:
Start investigating insurance as soon as you are seriously considering the property.
Are Parts of Yucaipa in Wildfire Hazard Zones?
Yes.
The City of Yucaipa maintains an official Fire Hazard Severity Zones resource where residents and buyers can review local wildfire information and mapping.
California’s updated mapping includes three categories:
- Moderate
- High
- Very High
Yucaipa’s foothill setting means wildfire preparedness is an important local issue.
However, don’t make the mistake of assuming:
“This property is in a fire-hazard zone, so I can’t insure it.”
That is not how the system works.
The Office of the State Fire Marshal specifically provides a consumer notice explaining that its Fire Hazard Severity Zone maps do not directly establish homeowners insurance rates or availability.
Insurance companies use separate underwriting and risk models.
That is why the best answer for a particular property comes from getting actual insurance quotes.
What About Fire Hazard Zones in Redlands?
Redlands also has mapped Moderate, High and Very High Fire Hazard Severity Zones.
The City of Redlands provides an official Fire Hazard Severity Zone map and wildfire-safety resource.
This can be especially important for buyers considering properties closer to hillsides, canyons, open space or vegetation.
But again:
A wildfire-hazard map is not an insurance quote.
Use the map to educate yourself about the property and surrounding area.
Then have a licensed insurance professional evaluate the actual home.
What Is a Fire Hazard Severity Zone?
A Fire Hazard Severity Zone, often abbreviated FHSZ, identifies areas based on the potential severity of wildfire conditions.
According to the California Office of the State Fire Marshal, the mapping considers factors such as:
- Vegetation
- Topography
- Climate
- Fire history
- Potential fire behavior
- Ember production and movement
An important distinction is that hazard and risk are not exactly the same thing.
The map describes the wildfire hazard expected in an area.
An insurer may evaluate many additional details when assessing an individual property.
Five Questions I Would Ask About Insurance Before Buying
1. Can I Get Coverage on This Specific Address?
Do not rely on what happened with the house next door.
Do not rely on what the seller currently pays.
And definitely do not assume the premium shown in an online home-payment calculator will be accurate.
Give the exact property address to a licensed insurance agent or broker.
2. What Will the Annual Premium Actually Be?
This is the number that matters for your budget.
Your lender’s initial estimate may simply use a placeholder insurance amount.
Once you have a real quote, ask your lender to update your estimated monthly housing payment.
You can also use the calculator on my Home Buying Consultation page to see how different insurance amounts affect your total estimated payment.
3. What Does the Policy Cover?
Price matters.
Coverage matters more.
Ask the insurance professional to explain:
- Dwelling coverage
- Personal-property coverage
- Liability coverage
- Loss-of-use or additional-living-expense coverage
- Deductibles
- Water-related limitations
- Wildfire-related coverage
- Any exclusions or special endorsements
California’s Department of Insurance has a detailed Homeowners and Renters Insurance Guide that can help consumers understand common policy terms.
4. Is This a Standard Homeowners Policy?
Ask whether the quote is for a traditional homeowners policy or another type of coverage.
That becomes especially important when discussing the California FAIR Plan.
5. Are There Improvements That Could Affect the Property’s Insurance Profile?
Ask whether features such as the roof, vents, landscaping or other wildfire-mitigation improvements matter to the insurer.
California has a program specifically designed around this issue called Safer from Wildfires.
What Is the California FAIR Plan?
You may hear the term FAIR Plan when discussing California homeowners insurance.
The California Department of Insurance explains the FAIR Plan as an option for property owners who cannot obtain insurance through the regular market.
Think of it as a safety-net option, not automatically the first place every buyer should go.
The Department of Insurance recommends shopping the regular insurance market before turning to the FAIR Plan.
This is important because FAIR Plan coverage is not necessarily the same as a traditional homeowners policy.
Does the FAIR Plan Cover Everything a Normal Homeowners Policy Does?
No.
This is where buyers need to pay attention.
The California Department of Insurance explains that the basic FAIR Plan policy provides more limited coverage than a traditional homeowners policy.
Depending on the situation, consumers may need additional coverage—often called a Difference in Conditions, or DIC, policy—to fill certain coverage gaps.
Do not assume:
“I have a FAIR Plan policy, so everything is covered.”
Ask a licensed insurance professional to explain exactly what is covered, what is excluded and whether additional coverage is recommended.
Where Can Buyers Look for Homeowners Insurance?
California’s Department of Insurance has created a useful tool called the Home Insurance Finder.
You can enter a ZIP code or city and search for licensed companies and insurance professionals.
There is even an option to narrow the search toward companies that may write policies in higher-fire-risk areas.
The Department cautions that appearing in the tool does not guarantee a company will accept a particular property, but it gives consumers a place to begin.
This is one of those government resources worth bookmarking if you are buying in our area.
Don’t Stop After One Insurance Company Says No
This is important.
One insurance company’s decision does not necessarily mean every company will make the same decision.
The California Department of Insurance recommends shopping around and contacting multiple insurers or licensed agents when consumers are having difficulty finding residential coverage.
Its Top Ten Tips for Finding Residential Insurance provides a good checklist.
If I were buying, I would not make a major decision based on one phone call.
Get several opinions when appropriate.
Ask About Wildfire-Mitigation Discounts
This is one area where homeowners should know that California has made changes.
The California Department of Insurance’s Safer from Wildfires program identifies property and community wildfire-mitigation measures that can qualify for insurance discounts.
The program looks at improvements such as:
- A Class A fire-rated roof
- An ember-resistant area near the structure
- Ember- and fire-resistant vents
- Noncombustible materials at the bottom of exterior walls
- Enclosed eaves
- Appropriate vegetation management
- Clearing combustible materials beneath decks
- Certain community-wide wildfire-safety efforts
Not every insurance company calculates discounts in exactly the same way.
Ask your insurance professional:
“Does this home qualify for any wildfire-mitigation discounts, and what documentation do you need?”
That is a much better question than simply assuming a house is either “good” or “bad” because of its location.
What Is Home Hardening?
Home hardening means improving a structure so it is more resistant to ignition from wildfire, embers, radiant heat and direct flame.
CAL FIRE has an excellent Home Hardening guide explaining areas homeowners can evaluate.
These may include:
- Roof
- Rain gutters
- Vents
- Eaves and soffits
- Windows
- Exterior walls
- Decks
- Fences
- Garage doors
If you are purchasing an older home, do not automatically assume it has the same wildfire-resistant building features as newer construction.
An inspector, contractor, fire-safety professional and insurance professional can each help evaluate different parts of the picture.
What Is Defensible Space?
Defensible space is the buffer between a structure and surrounding vegetation or other combustible materials.
CAL FIRE provides a detailed Defensible Space guide describing vegetation-management practices around structures.
For buyers, look at more than the house itself.
Pay attention to:
- Trees touching or overhanging the roof
- Dead vegetation
- Leaves and debris in gutters
- Shrubs directly against the house
- Combustible materials underneath decks
- Wood fencing attached directly to the structure
- Vegetation on slopes
- Nearby outbuildings
This does not mean you should diagnose wildfire risk yourself.
It means you should know what questions to ask.
The Roof May Matter More Than the Countertops
Here is where my real-estate brain kicks in.
Buyers naturally notice:
Quartz countertops.
New flooring.
Pretty paint.
I notice those things too.
But when we are looking at a home in an area where wildfire preparedness matters, I also want to know:
How old is the roof?
What material is it?
What condition is it in?
What do the vents look like?
Is vegetation touching the structure?
Are there large trees over the roof?
The things that aren’t glamorous can sometimes matter far more than the things that photograph beautifully.
Yucaipa Buyers: Check Insurance Before You Get Too Far Into the Deal
If you are browsing homes for sale in Yucaipa, add insurance research to your property checklist.
Especially when considering foothill, canyon-adjacent or open-space locations, I recommend asking about insurance early.
Your process might look like this:
- Find a home you seriously like.
- Review available seller disclosures.
- Review applicable natural-hazard information.
- Check official wildfire mapping.
- Send the property address to an insurance professional.
- Obtain an actual quote.
- Ask what coverage is included.
- Give the premium estimate to your lender.
- Recalculate the complete monthly payment.
- Decide whether the numbers still make sense.
That is much better than discovering an unexpected expense just before closing.
If you are also working within a tighter budget, read my guide to homes for sale in Yucaipa under $500,000. Insurance is one of the expenses that should be considered alongside the mortgage payment, taxes and HOA fees.
Redlands Buyers Should Do the Same
If you are searching homes for sale in Redlands, the same rule applies:
Investigate the individual property.
Redlands includes everything from historic homes and established neighborhoods to properties closer to foothills and open space.
That variety means you should not assume that an insurance experience on one side of town applies to another property.
Historic or older homes can also present additional questions involving:
- Roof age and material
- Electrical systems
- Plumbing
- Building materials
- Replacement cost
- Renovation history
- Wildfire-mitigation features
A charming house can still be a wonderful purchase.
I just want you to know what you are buying.
What Sellers in Yucaipa and Redlands Should Know
This isn’t only a buyer issue.
If you are thinking about selling, insurance questions may come up from prospective buyers.
Consider gathering information about:
- Roof age
- Recent roof replacement
- Updated vents
- Tree trimming
- Vegetation management
- Exterior improvements
- Home-hardening work
- Firewise or community wildfire-safety participation, if applicable
- Permitted improvements
Keep receipts and documentation when you complete significant property improvements.
That information may be useful when buyers, inspectors or insurance professionals ask questions.
If you are considering selling, you can also request my personalized home-value estimate so we can look at your property’s current market position and preparation strategy.
Don’t Choose a House Based Only on an Insurance Quote
Insurance matters.
But it is still only one part of the purchase.
We also need to evaluate:
- Price
- Property condition
- Location
- Mortgage payment
- Taxes
- HOA dues
- Inspection findings
- Commute
- Future maintenance
- Your long-term goals
A property with a higher insurance premium may still make sense because of its purchase price or other features.
Another home with a lower premium may require expensive repairs.
The goal is to compare the whole cost of ownership.
My Buyer Checklist for Home Insurance in Yucaipa and Redlands
Before removing important purchase contingencies, consider discussing these questions with the appropriate professionals:
Insurance
- Can I insure this exact address?
- What is the annual premium?
- What is the deductible?
- What coverage am I receiving?
- Are there important exclusions?
- Is this a standard homeowners policy?
- Would I need FAIR Plan and additional coverage?
- Are wildfire-mitigation discounts available?
Property
- What is the roof age and condition?
- What type of roof is installed?
- Are vents ember-resistant?
- Is vegetation maintained?
- Are trees overhanging the structure?
- Are gutters clear?
- Are there wood fences attached to the home?
- Are there decks or outbuildings that deserve additional evaluation?
Location
- What does the official Fire Hazard Severity Zone map show?
- Is the home close to open space or a canyon?
- What evacuation information is available?
- What wildfire-preparedness programs are available locally?
Budget
- What is the complete monthly housing payment after adding actual insurance?
- Am I still comfortable with the payment?
- Do I have reserves after closing?
- Could future maintenance or mitigation improvements affect my budget?
Frequently Asked Questions About Home Insurance in Yucaipa and Redlands
Can you get homeowners insurance in Yucaipa?
Yes, homeowners insurance is available in Yucaipa, but availability, price and policy terms vary by property and insurer.
The best way to know what applies to a particular home is to obtain quotes for that exact address from licensed insurance professionals.
Can you get homeowners insurance in Redlands?
Yes. As with Yucaipa, availability and premiums vary by insurer and individual property.
Buyers should obtain property-specific quotes rather than relying on citywide assumptions.
Does being in a Fire Hazard Severity Zone automatically increase my insurance rate?
Not automatically.
CAL FIRE’s Fire Hazard Severity Zone mapping identifies wildfire hazard, but the State has specifically explained that those maps do not directly determine homeowners insurance rates or availability.
Insurance companies use their own underwriting and risk models.
What is the California FAIR Plan?
The California FAIR Plan is an insurance safety-net option for property owners who cannot obtain coverage through the regular insurance market.
Consumers should understand that FAIR Plan coverage is more limited than a standard homeowners policy and may need to be paired with additional coverage.
Should I get an insurance quote before making an offer?
You can start asking insurance questions whenever you are seriously considering a property.
At minimum, I recommend investigating coverage as early in the purchase process as practical and before making important contingency decisions.
Can home-hardening improvements reduce insurance costs?
California’s Safer from Wildfires regulations require insurers to offer discounts for qualifying wildfire-mitigation actions.
Actual discounts and requirements vary by insurer and property, so ask the insurance company or broker what documentation is required.
Where can I check Yucaipa wildfire zones?
Use the official City of Yucaipa Fire Hazard Severity Zones page or the California Office of the State Fire Marshal.
Where can I check Redlands wildfire zones?
Use the City of Redlands’ official Community Wildfire Safety and Fire Hazard Zone Map resource.
Where can I look for California home insurance companies?
The California Department of Insurance provides a Home Insurance Finder that allows consumers to search for licensed insurance companies and agents, including an option related to higher-fire-risk areas.
The Bottom Line
If you remember only one thing from this article, make it this:
Don’t wait until the end of escrow to start thinking about homeowners insurance.
And don’t automatically walk away from a property simply because you see a wildfire-hazard designation.
Get the facts.
Check the official maps.
Talk with a licensed insurance professional.
Obtain an actual quote.
Understand the coverage.
Then look at that information alongside the price, mortgage payment, property condition and everything else that matters to you.
Buying a home is a big decision. You deserve to make it with good information instead of surprises.
If you are considering buying in Yucaipa or Redlands, I can help you identify properties, evaluate the real-estate side of the purchase and coordinate the process while you work directly with qualified insurance and lending professionals on those areas of expertise.
Browse homes for sale in Yucaipa, explore homes for sale in Redlands, schedule a free home-buying consultation, or contact me directly.
Casey Garduno, REALTOR®
CENTURY 21 Lois Lauer Realty
Call or text: (909) 553-0927
soldbycasey.com
CA DRE #01262961
This article provides general real-estate and educational information only. Casey Garduno is not an insurance agent and does not provide insurance, legal, tax or financial advice. Insurance availability, premiums, coverage, underwriting standards and wildfire requirements vary by property and provider and can change. Buyers and homeowners should consult licensed insurance professionals and verify current requirements with the appropriate government agencies.